Finance
SIP vs Lump Sum: How Do These Two Investment Approaches Differ?
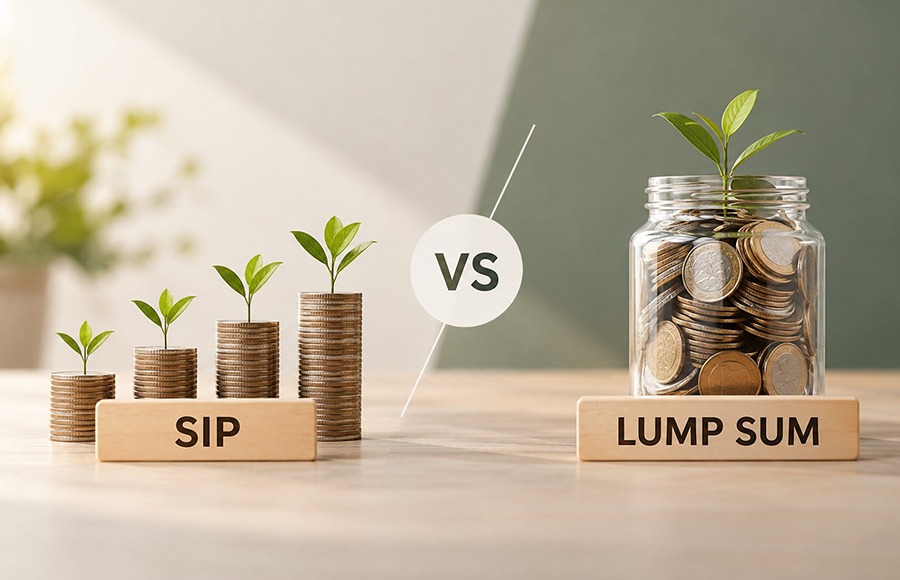

Investing is not just about choosing the right mutual fund. It is also about deciding when and how to invest your money. Two popular approaches are a Systematic Investment Plan (SIP) and a lump sum investment. While both allow investors to participate in mutual funds, they differ in timing, cash requirements and exposure to market fluctuations.
Understanding SIP vs lump sum investing can help you choose an approach that suits your financial goals, income and risk tolerance. Neither method guarantees better returns, and the right choice depends on your individual circumstances.
What Is a SIP Investment?
A Systematic Investment Plan (SIP) allows you to invest a fixed amount in a mutual fund at regular intervals, usually monthly. Instead of investing a large amount at once, you contribute smaller amounts over time.
For example, investing ₹5,000 every month through a SIP means contributing ₹60,000 over 12 months, excluding any returns or changes in investment value.
The key advantage is consistency. SIPs encourage disciplined investing without requiring you to predict the best time to enter the market. They also use rupee-cost averaging, whereby a fixed investment amount purchases more mutual fund units when prices are lower and fewer when prices are higher.
However, rupee-cost averaging does not eliminate market risk or guarantee profits. The value of your investment can still decline.
What Is a Lump Sum Investment?
A lump sum investment involves investing a substantial amount of money in a mutual fund in one transaction. This approach may suit investors who have surplus funds available through savings, a bonus, an inheritance or the sale of an asset.
For instance, instead of investing ₹5,000 every month, you could invest ₹60,000 in the same mutual fund at once.
The entire amount begins participating in the market immediately. If the investment performs well, you benefit from the growth of the full amount from the outset. However, if the market declines shortly after you invest, your entire investment is exposed to that fall.
Lump sum investing can work well for investors with a suitable investment horizon and the financial capacity to withstand market fluctuations. Nevertheless, entering at an unfavourable time can affect short-term results.
SIP vs Lump Sum: Key Differences
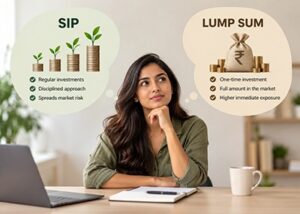
Investment method: SIP involves investing a fixed amount at regular intervals, whereas lump sum investing involves investing a larger amount in a single transaction.
Initial capital: SIP requires smaller periodic contributions, while lump sum investing requires the full investment amount upfront.
Market timing: SIP spreads investments across different market conditions, while lump sum investing exposes the entire amount to market movements from the outset.
Investment discipline: SIP encourages regular investing and financial discipline, whereas lump sum investing requires a deliberate decision about when to deploy available capital.
Suitability: SIP may suit investors with regular income who prefer gradual investing, while lump sum may suit investors with surplus capital and the ability to withstand market fluctuations.
Market risk: SIP reduces dependence on a single entry date but does not eliminate market risk. Lump sum investing involves immediate exposure of the entire amount to market movements.
Important: Neither approach guarantees better returns. The right choice depends on your financial goals, investment horizon, available funds and risk tolerance.
Which Is Better: SIP or Lump Sum?
There is no universal winner in the SIP vs lump sum debate. Your financial circumstances should guide the decision.
Choose SIP if you:
- Earn a regular monthly income and want to invest consistently.
- Prefer spreading purchases across different market conditions.
- Are building a portfolio gradually towards long-term financial goals.
- Want an investment routine that requires less attention to market entry timing.
Consider lump sum investing if you:
- Already have surplus money available for investment.
- Have a sufficiently long investment horizon.
- Understand the potential impact of short-term market declines.
- Can invest without compromising emergency savings or near-term financial commitments.
If you have a large amount available but feel uncomfortable investing it all at once, you may consider a phased approach. However, staggering an existing sum does not automatically produce better returns than investing it immediately.
How to Choose the Right Investment Approach
Before investing, assess your financial goals, time horizon, risk tolerance and available cash. Keep an adequate emergency fund separate from investments exposed to market risk, particularly if you may need the money soon.
Also, choose a mutual fund based on its investment objective, risk profile, costs and suitability for your goals, rather than assuming that either SIP or lump sum will deliver superior returns.
For investors seeking personalised guidance, reviewing these factors with a qualified financial professional can help clarify the options.
Conclusion
SIP and lump sum investing offer different ways to enter the mutual fund market. SIP supports regular investing and spreads purchases over time, while lump sum investing deploys available capital immediately. Neither guarantees profits or protects against losses.
The best approach is the one that aligns with your financial goals, available funds and ability to manage risk. Explore your investment options carefully and make informed decisions that support your long-term financial plan.
Tags
Related Posts

Health
Screen Time and Your Eyes: What Long Hours on Devices Can Really Do to Your Eyes
From checking emails and attending online meetings to scrolling through social media,…
Sports
How Sports Leagues Are Creating New Career Opportunities Beyond Athletes
Sports leagues are no longer defined solely by the athletes competing on…
Travel
How Railway Journeys Are Becoming Part of the Travel Experience Again
There was a time when a train journey was simply a way…